English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
Lake Michigan Fishing Charter Indiana for an Unforgettable Fishing Adventure
Other |
2026-10-14 00:03:26
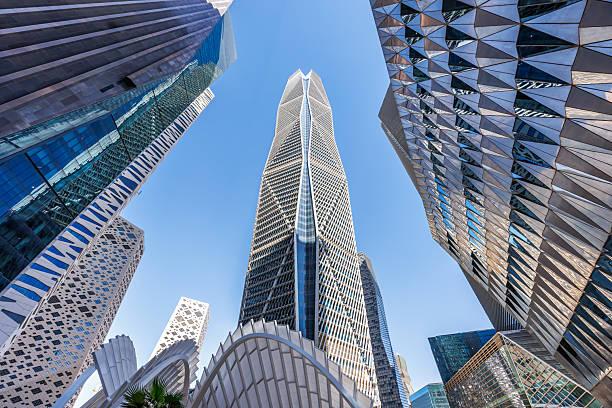
Public Private Partnerships (PPPs) are becoming increasingly important in Saudi Arabia as the Kingdom expands its infrastructure capabilities under Saudi Vision 2030. Major investments in transportation, water, energy, healthcare, logistics, and urban development require effective financial planning and a clear understanding of project risks. Modeling risk allocation in Saudi infrastructure PPPs helps government authorities, private investors, lenders, and project developers determine which party should manage specific risks throughout a project's lifecycle. Accurate Financial modeling services support this process by evaluating project costs, financing requirements, expected returns, cash flow uncertainties, and potential financial losses before contractual commitments are finalized.
Saudi Arabia's expanding privatization strategy is creating new opportunities for private sector participation in infrastructure development. A Business Consultancy Firm can support project stakeholders by evaluating commercial feasibility, reviewing contractual responsibilities, assessing financial exposure, and identifying risks that could affect long term project performance. Effective risk allocation is particularly important for large infrastructure developments because construction delays, cost inflation, regulatory changes, financing conditions, and operational challenges can influence project profitability and public service delivery. A structured approach allows stakeholders to establish realistic responsibilities while maintaining financial sustainability.
Risk allocation refers to the process of identifying project uncertainties and assigning responsibility for managing their financial and operational consequences to the party best positioned to control them. In infrastructure PPP arrangements, the government and private sector collaborate to develop, finance, construct, operate, and maintain public infrastructure.
Each party has different capabilities, resources, and responsibilities. Government authorities generally manage public policy, land access, regulatory approvals, and public service requirements. Private investors and project companies typically assume responsibilities related to financing, construction, technology, maintenance, and operational performance.
However, assigning every risk to the private sector does not automatically create an effective partnership. Excessive risk transfer can increase financing costs, reduce investor interest, and make projects commercially unviable. Similarly, retaining too many risks within the government can weaken the financial benefits of private sector participation.
An effective allocation framework should consider:
The party with the greatest ability to control a particular risk.
The financial capacity of each stakeholder to absorb potential losses.
The availability of insurance and other risk mitigation mechanisms.
The impact of uncertainty on project cash flows and debt repayment.
The contractual responsibilities of government authorities and private investors.
The potential consequences for public services if a risk materializes.
The objective is to distribute responsibilities fairly while protecting project affordability, bankability, and long term performance.
Saudi Arabia's infrastructure investment environment is undergoing significant development. The National Privatization Strategy, launched on 29 January 2026, represents an important step toward expanding private sector participation and improving public service delivery.
The previous privatization program developed more than 200 approved projects, representing approximately $213 billion in investment. Nearly 90 contracts were signed across different sectors. The new National Privatization Strategy targets more than 220 PPP contracts by 2030 and private sector capital investments exceeding $64 billion. It also identifies more than 145 priority privatization opportunities across the Kingdom.
These targets demonstrate why structured financial risk assessment is becoming increasingly important. A growing number of infrastructure projects will require investors to evaluate construction exposure, revenue uncertainty, financing structures, operational costs, and government obligations.
The FY2026 Saudi budget provides further context for infrastructure planning:
Total government expenditure is projected at SAR 1,313 billion.
Total government revenue is estimated at SAR 1,147 billion.
The projected budget deficit is approximately SAR 165 billion, equivalent to around 3.3% of GDP.
Public debt is projected to reach SAR 1,622 billion.
Infrastructure and transportation expenditure is allocated approximately SAR 35 billion.
These figures highlight the importance of balancing infrastructure development with fiscal sustainability. PPP structures can mobilize private capital, but their long term payment obligations and contingent liabilities must be assessed carefully.
Infrastructure PPP projects involve several categories of risk. Their significance depends on the sector, project location, financing arrangement, construction requirements, and concession period.
Construction risk is one of the most significant uncertainties in infrastructure PPP projects. It includes delays, contractor failures, design errors, labor shortages, material price increases, and unexpected site conditions.
In Saudi Arabia, large scale infrastructure projects may involve complex engineering requirements, challenging environmental conditions, and extensive supply chains. Delays can increase financing costs and postpone the commencement of revenue generation.
For example, a transportation infrastructure project that experiences a 12 month construction delay may face additional interest expenses, contractor claims, and reduced operating revenue during the affected period.
Risk allocation models should establish:
Construction completion milestones.
Contractor performance guarantees.
Delay penalties and compensation mechanisms.
Contingency allowances for unexpected costs.
Clear procedures for approving design modifications.
Responsibilities for land access and site preparation.
Private contractors should generally manage risks within their control, while government authorities may retain responsibility for specific land acquisition or public approval issues.
Demand risk occurs when actual infrastructure usage is lower than the forecasts used during project development.
For example, a toll road operator may expect a particular number of vehicles each day. If traffic volumes remain below expectations, toll revenue may not be sufficient to cover operating expenses, debt repayments, and investor returns.
Similarly, airports, ports, public transportation networks, and commercial infrastructure facilities depend on user demand and economic activity.
Demand risk modeling should evaluate:
Expected user volumes.
Customer payment behavior.
Changes in economic activity.
Competition from alternative infrastructure.
Population growth and urban development.
Changes in transportation and logistics requirements.
A project may use minimum revenue support, availability payments, or carefully structured concession arrangements to manage excessive demand uncertainty. However, government support must be evaluated against its potential fiscal cost.
Infrastructure projects frequently require substantial initial capital investment. Their financing structures may combine equity, commercial loans, Islamic financing, development finance, and institutional investment.
Changes in financing costs can significantly affect project profitability, particularly when a project uses variable interest rate facilities or requires refinancing during a long concession period.
Financial models should assess changes in borrowing costs, debt repayment schedules, interest coverage, and financing availability.
For example, a 1% increase in the financing rate may significantly increase the total cost of borrowing for a project with substantial outstanding debt.
Risk allocation agreements should establish which party is responsible for refinancing exposure, changes in financing conditions, and delays in achieving financial close.
Saudi infrastructure projects operate within a developing regulatory environment. Changes in licensing requirements, environmental standards, taxation, land regulations, and sector specific policies can affect project economics.
Government authorities are generally better positioned to manage changes in public policy, while private investors should remain responsible for complying with established regulations and contractual requirements.
Contracts should distinguish between general legal changes, project specific regulatory changes, and changes that directly affect the financial position of the project company.
This distinction helps avoid disagreements about compensation and contractual adjustments.
Operational risk arises after the infrastructure asset becomes commercially operational. It includes equipment failures, maintenance requirements, service interruptions, cybersecurity incidents, and higher than expected operating costs.
A PPP operator may be responsible for maintaining a road, water transmission system, airport facility, or public transportation network throughout the concession period.
Performance based contracts can reduce operational uncertainty by linking payments to measurable service standards.
Important performance indicators include:
Asset availability.
Maintenance completion rates.
Service interruption frequency.
Equipment reliability.
Customer satisfaction.
Compliance with safety standards.
Clear performance requirements help ensure that infrastructure assets deliver consistent services throughout their operating lives.
A structured risk allocation framework helps stakeholders identify, evaluate, distribute, and monitor project uncertainties. It should be developed during the feasibility and procurement stages rather than after the main contractual terms have been finalized.
The first step is to identify all potential risks that could affect project delivery and financial performance. Stakeholders should examine the complete project lifecycle, from initial planning and land acquisition to construction, operation, maintenance, and asset transfer.
Risks should be classified into different categories to make their assessment more systematic.
Common risk categories include:
Commercial risks: Lower demand, reduced revenue, customer payment defaults, and market competition.
Financial risks: Interest rate fluctuations, refinancing difficulties, inflation, and currency exposure.
Construction risks: Project delays, contractor performance, material shortages, and cost overruns.
Regulatory risks: Changes in legislation, licensing requirements, and government policies.
Environmental risks: Climate conditions, water availability, pollution, and environmental compliance.
Operational risks: Equipment failure, maintenance expenses, service interruptions, and technology problems.
Political and force majeure risks: Extraordinary events, political developments, and circumstances outside the reasonable control of the contracting parties.
A comprehensive risk register should document the probability, potential financial impact, responsible party, mitigation strategy, and monitoring requirements for each identified risk.
After identifying project risks, stakeholders must determine which party can manage each uncertainty most effectively.
The government may be better positioned to manage land acquisition, public approvals, and certain policy related risks. Meanwhile, private developers generally have greater control over construction management, equipment selection, maintenance planning, and operational efficiency. Risk ownership should be based on practical control rather than simply transferring financial responsibility to another party.
For example, transferring unpredictable land acquisition delays to a private developer may increase the project's contingency requirements without reducing the underlying uncertainty. A more balanced agreement would allocate land access responsibilities to the relevant government authority while requiring the developer to meet construction milestones once access is provided.
Risk quantification converts identified uncertainties into measurable financial impacts. This step helps stakeholders understand how different events may affect project investment requirements, operating costs, and expected returns.
Financial modeling services can help evaluate these exposures through integrated financial forecasts, scenario analysis, sensitivity testing, and probability based assessments.
Consider a hypothetical infrastructure project with an initial investment of SAR 2 billion. Its financial model may examine the following scenarios:
Construction costs increased by 10%, creating an additional investment requirement of SAR 200 million.
Construction is delayed by 6 months, increasing financing and project management expenses.
Operating costs increase by 8%, reducing annual operating margins.
Actual demand falls by 15%, affecting projected revenue and debt repayment capacity.
These scenarios help stakeholders determine which risks require insurance, contractual guarantees, financial reserves, or alternative allocation arrangements.
A risk allocation matrix provides a structured record of how project responsibilities are distributed between the government and private sector participants.
Saudi Arabia's National Center for Privatization and PPP has introduced an official Risk Allocation Matrix Template as part of its PPP guidance framework. The templates became effective on 1 January 2026 and support the preparation of project studies, tendering documents, agreements, and commercial arrangements.
The matrix helps project stakeholders establish:
The description of each identified risk.
The party responsible for managing the risk.
The party bearing the financial consequences.
Risk mitigation and insurance requirements.
Compensation arrangements when specified events occur.
Contractual procedures for resolving disputes.
The matrix should reflect the actual characteristics of each project. A water transmission project, for example, will have different operational and environmental exposures from a highway or airport concession.
Financial modeling is an essential component of PPP risk management because it connects contractual responsibilities with measurable financial outcomes.
A financial model translates project assumptions into projected revenue, expenditure, cash flow, financing requirements, and investor returns. It also demonstrates how different risk allocation decisions can change the financial position of government authorities and private investors.
An integrated financial model should cover the complete project lifecycle. It should include development expenditure, construction costs, financing arrangements, operational revenue, maintenance expenses, taxes, and asset transfer obligations.
The model should generally include:
Initial capital expenditure and construction schedules.
Equity contributions and debt financing.
Revenue forecasts and payment mechanisms.
Operating expenditure and maintenance reserves.
Financing costs and repayment schedules.
Tax obligations and working capital requirements.
Cash flow available for debt servicing.
Investor returns and project valuation.
Residual asset value and transfer costs.
The model should also distinguish between risks that affect project costs and those that influence revenue generation.
For instance, a fixed availability payment arrangement may reduce the private operator's exposure to user demand, but it does not eliminate construction, maintenance, or performance risks.
Sensitivity analysis measures how changes in individual assumptions influence the project's financial results.
It is particularly useful when stakeholders need to understand the financial consequences of uncertain variables before finalizing contractual terms.
For example, a project model may test:
A 5% increase in construction expenditure.
A 10% reduction in projected revenue.
A 2% increase in annual operating expenses.
A 1.5% increase in borrowing costs.
A 12 month delay in commercial operations.
The results can reveal which variables have the greatest influence on project returns and financing sustainability.
Sensitivity analysis also helps investors identify whether a project can withstand adverse market conditions without requiring additional government support.
Unlike sensitivity analysis, which generally changes individual assumptions, scenario analysis evaluates multiple interconnected changes.
For example, an infrastructure project may be assessed under three different operating environments.
Base Case Scenario
Construction follows the approved schedule.
Capital expenditure remains within the estimated budget.
Revenue reaches the expected level.
Operating expenses remain stable.
Downside Scenario
Construction costs increase by 10%.
Revenue decreases by 15%.
Financing costs increase by 1%.
Commercial operations begin 6 months later.
Upside Scenario
Construction is completed ahead of schedule.
Operating efficiency improves.
Demand exceeds the original forecast.
Maintenance expenses remain below budget.
Comparing these scenarios allows stakeholders to determine whether the proposed allocation of risks is financially reasonable under different conditions.
Lenders need confidence that a PPP project can generate sufficient cash flow to meet its financial obligations. Therefore, debt service coverage and financing sustainability should be evaluated throughout the concession period.
The debt service coverage ratio (DSCR) measures the cash available for debt repayment compared with scheduled principal and interest payments.
A model should examine how construction delays, reduced demand, higher maintenance expenses, and refinancing costs influence this ratio.
Investors should also evaluate:
Internal rate of return.
Net present value.
Equity cash flow.
Project operating margins.
Debt repayment capacity.
Payback period.
Long term capital requirements.
Financial modeling services provide an analytical foundation for comparing alternative financing structures and understanding whether the proposed distribution of risks supports acceptable investor returns.
Different infrastructure sectors require different risk allocation approaches. Saudi Arabia's infrastructure priorities include several industries where project economics and operational requirements vary considerably.
Transportation PPPs involve construction, traffic demand, safety, maintenance, and technology related risks. A toll road concession may expose private investors to traffic volume fluctuations. However, an availability based road contract may provide predictable government payments when the infrastructure meets agreed performance standards.
Saudi Arabia's One Stop Stations project provides an example of the scale and complexity of transportation related PPP opportunities. In February 2026, the project progressed with the qualification of participating groups and companies. It covers facilities across the Roads General Authority's 73,600 kilometre intercity road network and is structured around a 30 year design, build, finance, operate, and maintain contract. Its long operating period makes it important to model construction completion, facility utilization, maintenance costs, commercial revenue, and asset condition throughout the concession.
Water infrastructure projects involve substantial capital investment, energy consumption, environmental considerations, and long term operating obligations. A relevant example is the Jubail to Buraydah Independent Water Transmission Pipeline, which achieved financial close in October 2025.
The project includes:
A pipeline extending approximately 587 kilometres.
A daily water transmission capacity of 650,000 cubic metres.
A Build, Own, Operate, and Transfer structure.
Financing supported by the National Infrastructure Fund and 7 regional and local banks.
Water PPP models should evaluate electricity prices, transmission losses, maintenance requirements, equipment reliability, and water demand. The sector's wider importance is also reflected in demand projections. Saudi potable water demand is expected to reach approximately 17.08 million cubic metres per day by 2030, according to industry reporting published in April 2026. These conditions make long term operational and demand forecasting essential when assigning financial responsibilities.
Energy PPP projects may involve renewable energy generation, electricity transmission, storage facilities, and supporting infrastructure. Important risks include resource availability, equipment performance, technology changes, construction delays, and fluctuations in operating costs.
Risk allocation models should distinguish between risks associated with energy production and those related to grid connectivity or government procurement arrangements. Private developers can generally manage equipment selection, construction, and maintenance, while certain grid connection and public policy responsibilities may require government or utility involvement.
Healthcare PPP projects involve construction, facility availability, equipment maintenance, technology systems, and service quality. The private operator may be responsible for maintaining buildings and equipment, while public authorities retain responsibility for healthcare policy and public service standards.
Contracts should establish clear performance indicators to prevent disagreements about service quality, maintenance responsibilities, and payment adjustments. A financial model should also assess lifecycle maintenance expenses because healthcare infrastructure requires regular equipment upgrades and specialized facility management.
Strong governance is necessary to ensure that risk allocation arrangements remain effective throughout the project lifecycle. Even a well structured financial model cannot prevent disagreements if contractual responsibilities are unclear or monitoring systems are inadequate.
Government authorities, project companies, lenders, contractors, and operators should establish clear reporting procedures and accountability mechanisms.
PPP agreements should include provisions explaining how different risks will be managed when unexpected events occur.
Common contractual mechanisms include:
Performance guarantees: Require contractors and operators to meet agreed construction and operational standards.
Compensation events: Establish payment adjustments when specified events affect contractual obligations.
Insurance arrangements: Protect stakeholders against insurable construction, property, and operational losses.
Force majeure provisions: Define responsibilities when extraordinary events prevent contractual performance.
Change in law provisions: Explain how qualifying regulatory changes affect project obligations.
Termination provisions: Establish financial settlement procedures if the agreement ends prematurely.
These mechanisms help protect both public and private stakeholders while reducing the possibility of unexpected financial disputes.
Government guarantees, minimum revenue commitments, availability payments, and termination compensation can create financial obligations for public authorities. These obligations must be assessed carefully because they may affect future government budgets even when immediate expenditure is not required.
For example, a government guarantee may support project financing, but it could create substantial financial exposure if the project company fails to meet its debt obligations.
Risk monitoring should therefore include:
Total government guarantees.
Potential compensation payments.
Availability payment commitments.
Termination liabilities.
Revenue support arrangements.
Long term contractual payment obligations.
Regular reporting allows government authorities to understand their financial exposure and maintain fiscal discipline.
Risk allocation should not remain a one time exercise completed during procurement. Infrastructure conditions can change significantly throughout a concession period. Project stakeholders should regularly review risk registers, financial forecasts, construction progress, operational performance, and financing conditions. Monthly project reporting and quarterly financial reviews can help identify emerging issues before they become major financial problems.
Infrastructure PPP projects require expertise across financial planning, commercial evaluation, legal documentation, and operational management. A Business Consultancy Firm can help stakeholders assess project feasibility, evaluate alternative PPP structures, identify financial exposure, and improve the commercial terms of infrastructure agreements.
Professional advisory support can be particularly valuable during the following stages:
Project Feasibility Assessment
Advisors evaluate whether a proposed infrastructure project can generate sufficient economic and financial value. They examine capital requirements, expected demand, operating costs, financing options, and potential project risks.
Commercial Structuring
Project stakeholders need to identify an appropriate PPP model based on the nature of the infrastructure asset. Options may include Build, Operate, Transfer, Build, Own, Operate, Transfer, and Design, Build, Finance, Operate, and Maintain structures.
Financial Risk Evaluation
Specialists assess how different risk allocation arrangements influence project cash flows, investor returns, debt repayment, and government financial commitments.
Procurement and Contract Review
Advisory professionals help review tender requirements, contractual obligations, performance standards, and financial compensation mechanisms.
Project Performance Monitoring
Continuous financial and operational reviews help identify changes in project assumptions and determine whether existing risk mitigation arrangements remain appropriate.
Successful infrastructure PPP arrangements require consistent risk assessment and realistic financial assumptions. Stakeholders should follow several practices to improve project bankability and long term performance.
Each risk should be assigned to the stakeholder with the practical ability to prevent, manage, or reduce its consequences. This prevents unnecessary financial burdens and improves accountability.
Revenue forecasts, construction budgets, interest rates, operating expenses, and maintenance requirements should reflect realistic market conditions. Overly optimistic assumptions can create significant problems during project implementation.
Infrastructure assets require continuous maintenance, periodic upgrades, and eventual rehabilitation. Models should account for these expenses rather than focusing only on initial construction costs.
Financial forecasts should consider inflation, financing changes, demand fluctuations, and unexpected project delays. Scenario analysis helps stakeholders understand the financial resilience of different PPP structures.
Government authorities and private investors should clearly document their obligations, compensation rights, performance standards, and dispute resolution procedures.
Saudi Arabia's PPP regulatory framework continues to develop. Project stakeholders should follow applicable requirements issued by the National Center for Privatization and PPP and relevant government authorities.
Effective communication between lenders, developers, contractors, government entities, and operators helps identify potential problems early and reduces the likelihood of contractual disagreements.
Saudi Arabia's infrastructure development agenda is expected to create additional opportunities for private investors, international developers, financial institutions, and engineering companies.
The National Privatization Strategy provides a framework for expanding private sector participation across 18 targeted sectors, supported by 5 main programs and 42 executive initiatives. Its objective of achieving more than 220 PPP contracts by 2030 demonstrates the importance of improving project preparation and financial risk management. Several developments are likely to influence future risk modeling practices.
Greater Use of Digital Financial Models
Digital forecasting tools and integrated project management systems can improve the accuracy of financial assumptions and provide better visibility into project performance.
Increased Focus on Climate and Environmental Risks
Water scarcity, extreme temperatures, energy consumption, and environmental compliance will require greater attention during infrastructure planning.
Improved Bankability Assessment
Lenders and investors are increasingly focused on whether PPP projects have realistic financial structures and manageable risk exposure. Early market engagement and financial assessment can help identify potential financing challenges before procurement.
More Detailed Government Liability Assessment
As the PPP market expands, government authorities will need to monitor guarantees, payment commitments, and other contingent liabilities to protect long term fiscal sustainability.
Greater Private Sector Participation
The Kingdom's investment objectives are likely to attract additional domestic and international participation. However, sustainable investor interest will depend on transparent procurement, predictable contractual arrangements, and commercially reasonable risk distribution.
Modeling risk allocation in Saudi infrastructure PPPs is essential for delivering financially sustainable infrastructure projects under Saudi Vision 2030. Effective risk distribution helps government authorities, private investors, lenders, and project developers understand their responsibilities while reducing exposure to construction delays, financing uncertainties, operational challenges, and regulatory changes.
The Kingdom's National Privatization Strategy, infrastructure investment priorities, and updated PPP guidance framework are creating a stronger environment for private sector participation. These developments make comprehensive risk identification, financial forecasting, contractual planning, and continuous monitoring increasingly important.
By combining realistic financial assumptions, structured risk allocation matrices, scenario analysis, and transparent contractual arrangements, infrastructure stakeholders can improve project bankability and protect long term investment value. A disciplined approach to risk management will also support better public services, efficient infrastructure delivery, and sustainable economic development across Saudi Arabia.