English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
What Sets Raf Simons Apart in a Crowded Fashion Industry
Shopping |
2026-11-02 10:03:40
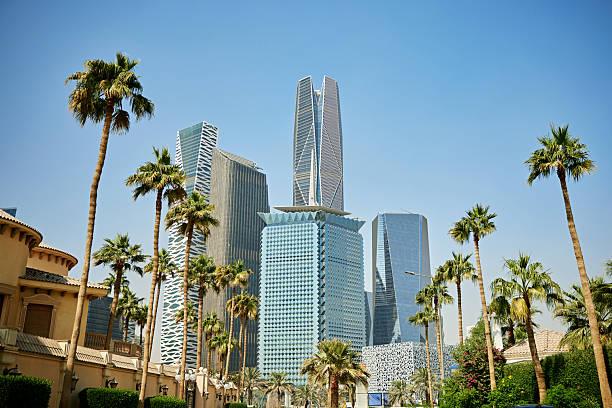
Internal auditing is becoming increasingly important for businesses operating in Saudi Arabia as regulatory expectations, digital transformation, cybersecurity threats, and corporate governance requirements continue to evolve. In 2026, organizations need auditors who can do more than review financial statements and examine operational procedures. They must identify emerging risks, evaluate internal controls, understand technology, and provide practical recommendations that improve organizational performance. As businesses expand across different sectors, experienced professionals working with internal audit firms are expected to combine technical expertise with analytical thinking, communication, and strategic decision making.
The changing business environment also requires closer collaboration between internal audit departments, senior management, and external financial experts. Financial consultants in Riyadh increasingly operate in an environment where financial transparency, regulatory compliance, effective risk management, and reliable reporting influence business decisions. Internal auditors must understand how financial operations connect with wider organizational objectives. They also need to develop competencies that support Saudi Vision 2030, particularly as investments in infrastructure, technology, financial services, tourism, and other non oil industries create more complex business operations.
Saudi Arabia's economic transformation is creating new expectations for governance and professional accountability. The Kingdom's non oil economy accounted for approximately 55% of GDP in 2025, while non oil activities recorded 4.9% growth. This expansion increases the importance of effective internal controls, financial oversight, and operational risk management. Consequently, internal audit professionals must continuously update their knowledge to remain relevant in the Kingdom's changing business environment.
Internal auditing has developed from a traditional compliance activity into a strategic business function. Organizations now expect auditors to evaluate whether governance structures, risk management processes, and internal controls are operating effectively.
Saudi businesses are also managing more complex responsibilities involving regulatory compliance, digital security, financial reporting, procurement, project management, and third party relationships. These responsibilities require professionals who understand both traditional auditing methods and emerging business risks.
The Institute of Internal Auditors introduced its Global Internal Audit Standards in 2024, with the standards becoming effective on January 9, 2025. These standards emphasize professional ethics, independence, governance, quality management, and effective internal audit performance.
The IIA also published its Internal Auditing Competency Framework practice guide in July 2025, providing guidance on identifying professional competencies, assessing proficiency, and supporting continuous development.
For Saudi organizations, these developments highlight the importance of investing in skilled audit professionals who can deliver meaningful assurance and advisory insights.
Several factors are increasing the demand for advanced internal audit capabilities:
Regulatory developments: Organizations must maintain appropriate compliance procedures and demonstrate accountability.
Digital transformation: Automated systems and digital operations require auditors to understand technology related risks.
Cybersecurity threats: Increasing dependence on digital infrastructure creates additional exposure to security incidents.
Business expansion: Large projects and diversified operations require stronger financial and operational controls.
Corporate governance: Boards and senior management need reliable information about organizational risks and control effectiveness.
Financial transparency: Accurate reporting and documented procedures support better investment and management decisions.
Developing the right competencies enables internal auditors to move beyond identifying mistakes and contribute to long term organizational improvement.
Risk assessment is one of the most important skills internal audit professionals need in 2026. Businesses face different types of risks, including financial uncertainty, operational disruptions, regulatory changes, cybersecurity incidents, supply chain challenges, and strategic failures. Auditors must understand how these risks affect organizational objectives and determine whether existing controls are sufficient to manage them.
Traditional auditing approaches often concentrate on reviewing historical transactions and checking whether established procedures were followed. Modern internal auditing requires a more forward looking approach. Professionals must identify potential threats before they create significant financial or operational consequences.
For Saudi organizations, risk assessment is particularly important because businesses are expanding into new industries and managing increasingly complex projects. Construction companies, financial institutions, healthcare providers, manufacturing businesses, and real estate organizations all face different risk exposures.
Internal auditors should develop the ability to:
Identify financial, operational, strategic, and compliance risks.
Evaluate the likelihood and potential impact of identified risks.
Assess whether existing internal controls are appropriate.
Prioritize high risk business activities.
Monitor changes in the internal and external business environment.
Develop risk based audit plans aligned with organizational objectives.
For example, a Saudi construction company managing several infrastructure projects may experience procurement delays, unexpected material costs, contractor disputes, and budget overruns. An experienced auditor should evaluate procurement approvals, contract management procedures, project cost reporting, and supplier performance.
Risk assessment also requires understanding the relationship between different business functions. A weakness in procurement may create financial losses, operational delays, and regulatory concerns simultaneously.
Professionals should therefore develop the ability to communicate risk findings to management in a clear and practical manner. Rather than simply identifying weaknesses, they should explain their potential consequences and recommend appropriate control improvements.
Data analytics has become an essential competency for internal audit professionals. Organizations generate large volumes of financial and operational information through accounting platforms, enterprise resource planning systems, customer databases, procurement software, and digital payment systems. Auditors who can analyze this information are better positioned to identify unusual transactions, recurring control failures, inefficiencies, and potential fraudulent activities.
The Institute of Internal Auditors' 2025 Pulse of Internal Audit research highlighted data analytics as a major technology priority. Its Vision 2035 survey found that 92% of chief audit executives considered data analytics an important technology skill for the future of the profession. However, only 28% reported high or advanced data analytics usage within their internal audit functions. This difference demonstrates why developing practical analytical capabilities is important in 2026. Internal audit professionals should become familiar with tools and techniques that help them examine large datasets efficiently.
Important capabilities include:
Using Microsoft Excel for financial analysis and transaction testing.
Understanding Power BI dashboards and data visualization.
Working with SQL to retrieve and examine organizational information.
Identifying unusual patterns in financial transactions.
Performing trend analysis and exception reporting.
Using automated audit software to improve testing efficiency.
For example, an auditor reviewing a company's accounts payable process can analyze thousands of supplier transactions to identify duplicate invoices, unusual payment amounts, and transactions processed outside normal business hours.
Similarly, data analytics can help identify repeated budget overruns, unusual inventory movements, and inconsistencies between procurement records and payment documentation.
Professionals should also understand data quality, access restrictions, and the limitations of automated analysis. Incorrect or incomplete information can produce misleading audit results.
As Saudi businesses continue investing in digital infrastructure, auditors with strong analytical capabilities will be better equipped to provide timely and evidence based recommendations.
Cybersecurity awareness is another critical skill for internal audit professionals in 2026. Organizations increasingly depend on cloud platforms, digital payment systems, connected applications, electronic records, and automated business processes. Although these technologies improve efficiency, they also introduce security vulnerabilities.
Internal auditors must understand how organizations protect confidential information, control system access, monitor suspicious activities, and respond to cybersecurity incidents.
Saudi Arabia's cybersecurity sector continues to expand. The National Cybersecurity Authority reported that the Kingdom's cybersecurity market reached SAR 16.3 billion in 2025, representing a compound annual growth rate of 10.7% between 2023 and 2025.
The same report identified more than 22,000 cybersecurity professionals in the Kingdom, demonstrating the growing importance of specialized security capabilities.
Additionally, the IIA's Cybersecurity Topical Requirement became effective on February 5, 2026. It establishes a consistent approach for assessing cybersecurity governance, risk management, and control processes.
These developments make cybersecurity knowledge increasingly relevant to internal audit responsibilities.
Auditors should understand the following areas:
Information security policies and procedures.
User access management and authorization controls.
Data protection and confidentiality requirements.
Incident response and business continuity arrangements.
Cloud computing and third party technology risks.
Network security and system monitoring.
Backup procedures and disaster recovery controls.
For instance, an internal auditor reviewing a financial institution should examine whether employees have access only to the systems and information necessary for their responsibilities.
The auditor should also evaluate password policies, access reviews, system change approvals, and procedures for reporting security incidents.
A further responsibility involves understanding how cybersecurity risks affect financial and operational performance. A security incident may lead to service interruptions, financial losses, regulatory consequences, and reputational damage.
Internal auditors do not need to become technical cybersecurity engineers. However, they must understand essential security concepts and know when specialized expertise is required.
Regulatory knowledge is fundamental for professionals working in Saudi Arabia's internal audit environment. Organizations must comply with applicable laws, regulatory requirements, financial reporting obligations, industry standards, and internal governance policies.
Internal auditors evaluate whether management has established appropriate procedures to meet these responsibilities. They also examine whether employees understand their compliance obligations and whether management monitors potential violations.
Saudi Arabia's business environment includes organizations operating under different regulatory frameworks. Depending on their activities, businesses may need to consider requirements issued by the Capital Market Authority, Saudi Central Bank, Zakat, Tax and Customs Authority, Ministry of Commerce, and other relevant authorities.
Professionals must understand which requirements apply to their organizations rather than relying on general compliance knowledge.
Important regulatory and governance skills include:
Understanding relevant Saudi laws and regulatory frameworks.
Reviewing internal policies and approval procedures.
Evaluating compliance monitoring arrangements.
Assessing corporate governance structures.
Examining documentation and reporting practices.
Identifying regulatory gaps and recommending corrective measures.
Monitoring changes in applicable regulatory requirements.
For example, an auditor working with a financial services organization should understand the relevant regulatory expectations concerning customer information, financial reporting, operational controls, and risk management.
Corporate governance knowledge is equally important. Auditors must understand the responsibilities of boards, audit committees, senior management, and operational departments.
They should also evaluate whether responsibilities are appropriately distributed and whether important decisions receive independent review.
The Institute of Internal Auditors' Global Internal Audit Standards emphasize the importance of independence, ethical conduct, and professional accountability. These principles help ensure that internal audit functions can provide objective assessments without inappropriate management interference.
Professionals who combine regulatory knowledge with practical governance experience can help organizations improve accountability and maintain stronger control environments.
Internal auditors must possess strong financial analysis skills to evaluate the financial health and operational performance of an organization. Understanding accounting records alone is not sufficient. Professionals should know how financial information reflects business activities and how weaknesses in financial controls can affect organizational performance.
Financial analysis enables auditors to identify unusual movements, investigate discrepancies, assess financial reporting accuracy, and evaluate whether organizational resources are being used effectively.
In Saudi Arabia, businesses are managing significant investments, expanding operations, and entering new markets. These activities require careful financial oversight and reliable reporting.
Internal audit professionals should develop knowledge in several financial areas:
Financial statement analysis.
Budgeting and forecasting.
Cash flow monitoring.
Revenue and expense verification.
Accounts payable and receivable controls.
Inventory valuation and reconciliation.
Capital expenditure reviews.
Financial reporting and accounting standards.
For example, an auditor reviewing a manufacturing company should examine production costs, inventory records, supplier payments, and revenue recognition procedures.
If the organization experiences declining profit margins, the auditor may investigate whether the issue relates to increasing material costs, inefficient procurement, inventory losses, or weaknesses in cost monitoring.
Financial understanding also allows auditors to evaluate whether management reports accurately represent organizational performance.
Collaboration with Financial consultants in Riyadh can provide additional perspectives on financial reporting, budgeting practices, and business performance when specialist expertise is needed.
Auditors should also understand how accounting standards influence financial statements and internal control requirements. Knowledge of International Financial Reporting Standards is particularly useful for organizations operating across multiple jurisdictions.
Strong financial analysis skills help internal auditors connect individual control weaknesses with their wider financial implications.
Artificial intelligence and automation are changing how organizations manage information, process transactions, evaluate performance, and make decisions. Internal audit professionals must understand these technologies because they influence both business operations and the audit process itself.
AI based applications can support document reviews, transaction monitoring, anomaly detection, risk analysis, and audit planning. Automation can also reduce repetitive work and help auditors examine larger volumes of information.
However, these technologies introduce additional risks involving inaccurate outputs, data privacy, system access, algorithmic bias, and insufficient human oversight.
The IIA's 2025 Pulse of Internal Audit research identified artificial intelligence as an important future technology skill, with 70% of chief audit executives identifying it as a technology priority in the Vision 2035 survey.
This highlights the importance of developing practical AI knowledge rather than treating automation as a purely technical responsibility.
Internal auditors should understand:
How AI applications process organizational information.
How automated decisions influence business activities.
Whether AI systems use reliable and appropriate data.
How access to automated systems is controlled.
Whether AI generated outputs receive human verification.
How organizations monitor automated processes.
Whether appropriate governance policies exist for AI adoption.
For example, a company may introduce an automated system to approve supplier invoices. Although the system can improve processing speed, auditors should evaluate whether approval limits are properly configured and whether unusual transactions are flagged for investigation.
They should also examine whether system changes are documented and whether authorized employees review automated decisions.
AI can improve audit efficiency, but it should not replace professional judgment. Auditors remain responsible for evaluating evidence, interpreting findings, and determining whether recommendations are appropriate.
Professionals who understand both the opportunities and limitations of AI will be better prepared to assess technology related risks and support responsible digital transformation.
Technical knowledge is essential, but internal audit professionals also need strong communication and interpersonal skills. Auditors regularly interact with department managers, finance teams, operational employees, executives, and audit committees.
They must communicate complex findings in a clear and understandable manner so that stakeholders can recognize risks and take appropriate action.
A technically accurate audit report may have limited value if management cannot understand the findings or their potential business consequences.
Effective communication involves more than writing reports. It includes asking relevant questions, listening to employees, discussing control weaknesses, and presenting recommendations objectively.
Important communication and problem solving capabilities include:
Writing clear and structured audit reports.
Presenting findings to senior management.
Conducting professional audit interviews.
Explaining technical and financial issues in simple language.
Resolving disagreements through evidence based discussions.
Identifying the root causes of control failures.
Recommending practical corrective actions.
Critical thinking is equally important because auditors must evaluate whether the information they receive is accurate, complete, and relevant.
For example, if an organization repeatedly experiences procurement delays, an auditor should not immediately assume that employees are failing to follow procedures.
The underlying issue may involve unclear approval responsibilities, insufficient supplier documentation, outdated procurement systems, or unrealistic purchasing timelines.
Identifying the root cause helps auditors recommend sustainable improvements instead of temporary solutions.
Professionals must also maintain independence and professional skepticism. They should examine supporting evidence rather than automatically accepting explanations provided by management.
Strong communication skills improve cooperation between internal audit departments and other business functions while helping organizations address weaknesses more effectively.
Internal auditors frequently manage multiple assignments, deadlines, stakeholders, and reporting responsibilities. Project management skills help professionals organize audit activities, allocate resources, monitor progress, and complete assignments efficiently.
Saudi organizations increasingly operate through complex projects involving construction, technology implementation, infrastructure development, financial investments, and operational expansion.
These projects require structured oversight to ensure that resources are managed properly and organizational objectives remain achievable.
Auditors must understand how to plan engagements, define audit scope, establish timelines, assign responsibilities, and monitor findings.
Important project management competencies include:
Preparing risk based audit schedules.
Defining engagement objectives and scope.
Managing audit documentation.
Coordinating with different departments.
Monitoring assignment progress.
Tracking corrective actions.
Preparing timely audit reports.
Evaluating the effectiveness of implemented recommendations.
For example, an internal audit professional reviewing a large infrastructure project may need to coordinate with procurement, finance, engineering, project management, and external contractors.
Without effective project management, important audit procedures may be delayed, evidence may remain incomplete, and critical findings may not receive timely attention.
Continuous professional development is another essential responsibility. The business environment changes rapidly, meaning that skills acquired several years ago may not fully address current audit requirements.
Professionals should regularly update their knowledge through professional training, industry publications, technical courses, and recognized certifications.
Useful professional qualifications include:
Certified Internal Auditor (CIA).
Certified Information Systems Auditor (CISA).
Certified Fraud Examiner (CFE).
Certified Public Accountant (CPA).
Chartered Accountant (CA).
Certification in Risk Management Assurance (CRMA).
The appropriate qualification depends on an individual's responsibilities, experience, and career objectives.
Professionals should also remain familiar with the Global Internal Audit Standards and emerging guidance from the Institute of Internal Auditors.
Continuous learning allows auditors to strengthen their technical capabilities, adapt to new risks, and maintain professional credibility.
Developing an effective internal audit function requires more than recruiting experienced professionals. Organizations must create an environment where employees receive appropriate training, access reliable information, and continuously improve their technical and professional capabilities.
Saudi businesses should adopt structured competency development programs that connect employee skills with organizational risks and strategic priorities.
The following practices can support stronger audit teams:
1. Conduct Regular Skills Assessments
Organizations should evaluate existing competencies and identify gaps in risk assessment, financial analysis, cybersecurity, regulatory compliance, and technology.
2. Invest in Professional Training
Training programs should reflect actual business requirements rather than focusing exclusively on theoretical auditing concepts.
3. Encourage Professional Certifications
Supporting employees in obtaining relevant certifications can strengthen technical knowledge and improve professional standards.
4. Introduce Technology Based Audit Tools
Organizations should provide suitable analytical software, automated testing capabilities, and secure access to relevant business information.
5. Improve Collaboration Across Departments
Internal auditors should maintain professional relationships with finance, compliance, IT, procurement, and operational teams while preserving their independence.
6. Monitor Audit Performance
Management should evaluate audit quality, engagement completion, reporting timelines, recommendation implementation, and the effectiveness of identified improvements.
7. Strengthen Knowledge Sharing
Internal audit teams should discuss emerging risks, previous audit findings, regulatory updates, and lessons learned from completed assignments.
Organizations may also benefit from engaging internal audit firms when specialist knowledge, independent assessments, or additional technical resources are required.
External expertise can help businesses evaluate their existing control frameworks, identify weaknesses, and improve audit methodologies. However, management should retain responsibility for establishing appropriate governance structures and ensuring that internal audit activities remain aligned with organizational objectives.
The future of internal auditing in Saudi Arabia will depend on professionals who can combine financial knowledge, technological awareness, regulatory understanding, and strategic thinking.
The Kingdom's digital and economic transformation is creating new responsibilities for organizations across financial services, real estate, construction, healthcare, manufacturing, and other industries.
Saudi Arabia's cybersecurity market reached SAR 16.3 billion in 2025, while the Saudi digital economy represented 16.0% of GDP in 2024. These developments highlight the importance of auditors who understand technology driven business operations and the risks associated with them.
The Institute of Internal Auditors' Middle East Risk in Focus 2026/2027 research also identifies geopolitical uncertainty and supply chain concerns as important regional risk priorities. Geopolitical uncertainty increased by 31 percentage points, becoming a top five risk for 60% of surveyed chief audit executives in the Middle East.
These findings indicate that internal audit professionals must remain adaptable and continuously reassess the risks affecting their organizations.
Businesses evaluating their internal audit capabilities should consider whether their teams possess the expertise to address emerging challenges. Working with experienced internal audit firms can also help organizations identify competency gaps and strengthen their internal control frameworks.
At the same time, collaboration with financial experts may support organizations that require additional financial analysis, reporting expertise, or guidance on complex business decisions.
The demand for skilled internal auditors will increasingly depend on their ability to deliver reliable assurance, identify emerging threats, and provide recommendations that improve organizational performance.
Internal auditing in 2026 requires a combination of technical expertise, analytical capabilities, business knowledge, and professional judgment. Risk assessment, data analytics, cybersecurity, regulatory compliance, financial analysis, artificial intelligence, communication, and project management are among the most important competencies professionals should develop.
For Saudi organizations, these skills are particularly relevant as economic diversification, digital transformation, and expanding business activities increase the complexity of governance and operational responsibilities.
Internal audit professionals who continuously improve their knowledge can provide more effective assurance, identify weaknesses before they become serious problems, and help management make informed decisions.
Organizations should therefore treat professional development as an ongoing investment rather than an occasional training activity. By developing capable teams, strengthening audit methodologies, and adopting appropriate technologies, businesses can establish more reliable internal control environments.
The role of internal auditing will continue to evolve as new regulations, technologies, and business risks emerge. Professionals who combine traditional auditing knowledge with modern business and digital capabilities will be better positioned to support sustainable growth and stronger corporate governance across Saudi Arabia.